Best Medical Insurance Companies in Kenya (2026): The Policy Gaps Most Buyers Miss
You asked whether maternity was covered. The answer was yes. You booked your preferred consultant at Aga Khan and expected your medical cover to carry the main cost.
The delivery bill was KES 290,000.
Your maternity sublimit was KES 200,000.
The remaining KES 90,000 was yours to pay — not because the policy failed, but because it worked exactly as written. “Covered” did not mean fully paid.
That is the problem with comparing medical insurance in Kenya by insurer name, premium, and headline inpatient limit. A policy can look strong on paper and still leave you exposed at the exact moment you need it.
That is why any serious search for the best medical insurance companies in Kenya should start with fit, not ranking.
Best for which hospital? Best for which family stage? Best for which claim scenario? Best under which waiting period?
This guide compares nine actual medical insurance schedules in Kenya to show where the gaps sit, what each option is best suited for, and what to confirm before you sign.
At Amssurity Insurance, we treat “best” as a policy-fit question, because the best cover is not the one that looks strongest in a brochure. It is the one that still makes sense when your family needs to claim.
For the broader foundation on how medical cover works, start with our guide to health insurance in Kenya, then return here for the policy-level details most buyers miss
Table of Contents
What this guide is really comparing
This guide does not rank the best medical insurance companies in Kenya by name recognition, brochure promises, or the biggest headline inpatient limit.
It compares selected medical insurance options by the gaps that usually matter at claim time:
- Maternity sublimits
- Cancer ceilings
- Hospital copayments
- Outpatient depth
- Waiting periods
- Exclusions
- Claim-time fit
The question is not:
Which is the best among the best medical insurance companies in Kenya?
The better question is:
Which policy is least likely to fail your household when maternity, cancer treatment, outpatient care, copayments, or waiting periods are actually tested?
That is the lens we use in this guide.
What changed in medical insurance in Kenya in 2026
By 2026, comparing medical insurance in Kenya is no longer just about finding the biggest inpatient limit.
The real question is what that limit does after SHA/SHIF coordination, private hospital costs, sublimits, copayments, waiting periods, and international cover rules are applied.
The old shortcut was simple:
Compare insurer, premium, and inpatient limit.
That shortcut is now risky.
1. SHA/SHIF changed the claims environment
Buyer risk:
Your private medical cover may not respond exactly the way buyers were used to under the old NHIF-era assumptions. Depending on the insurer, benefit category, and claim process, some claims may involve SHA/SHIF coordination, statutory rebates, or additional documentation.
Ask before buying or renewing:
- Is the claim settled gross or net of SHA/SHIF rebate?
- Does pre-authorisation require SHA/SHIF participation first?
- Which benefits are affected?
2. Private hospital costs kept rising
Buyer risk:
A policy that looked adequate last year may now carry yesterday’s numbers. This matters most for maternity, surgery, cancer treatment, diagnostics, specialist outpatient care, and premium private hospitals.
Ask before buying or renewing:
- What is the current billing estimate from your preferred hospital?
- Does your maternity sublimit still match that estimate?
- Will your cancer ceiling survive a serious treatment phase?
- Will your outpatient limit survive normal family usage?
- What copay applies at your preferred hospital?
3. International cover became part of the local decision
Buyer risk:
International private medical insurance may now be part of the Kenya advisory conversation, but it should not be treated as a direct substitute for local family medical insurance. Local and international covers solve different problems.
Ask before buying or renewing:
- Are you buying local cover, international cover, or do you need both?
- Where will treatment most likely happen?
- Is evacuation included?
- Can you access outpatient care locally?
- Who handles claims administration?
- What exclusions apply?
The practical implication
Medical insurance in Kenya should no longer be compared by headline inpatient limit alone.
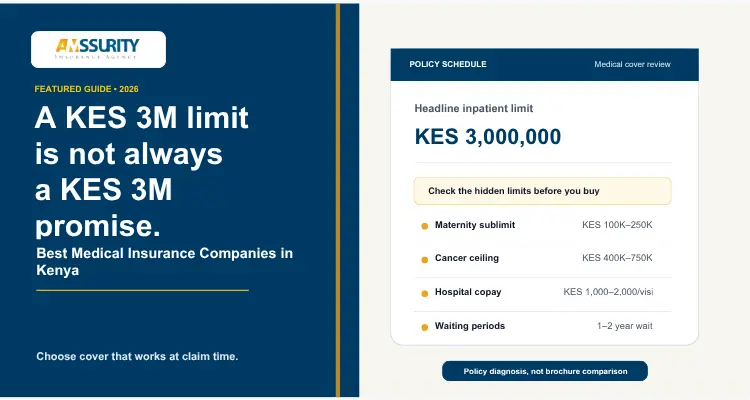
A KES 3M or KES 5M inpatient limit may still behave like a much smaller policy if the claim falls under a low maternity sublimit, a restricted cancer ceiling, a thin outpatient benefit, a premium hospital copay, a waiting period, or a SHA/SHIF coordination rule the buyer did not understand.
The better question is not:
Which insurer is most popular?
Or even:
Should I buy local or international cover?
The better question is:
Which structure matches where my family lives, where we seek treatment, and where the claim is most likely to happen?
Quick guide: Which buyer situation are you in?
Two families can buy medical cover from the same insurer and still need completely different protection.
A family planning maternity, a household with young children, a person managing a chronic condition, and someone living or working across borders are not buying the same kind of medical insurance — even when the insurer name is identical.
Use this table before comparing premiums or inpatient limits.
This is why “best medical insurance company in Kenya” is the wrong starting point. The right starting point is the claim scenario your household is most likely to face.
The mistake most buyers make when comparing medical insurance
Most Nairobi professionals searching for the best medical insurance companies in Kenya compare three things: the insurer’s name, the annual premium, and the headline inpatient limit.
That looks like due diligence. It can still leave you exposed.
What most buyers compare — and what it cannot tell you.
| What buyers compare | What it cannot tell you | Claim-time risk |
|---|---|---|
| Insurer name | Whether the policy fits your hospital, family stage, or likely claim scenario | You choose a familiar brand but miss the benefit structure |
| Annual premium | Whether the cheaper plan has weaker sublimits, waiting periods, or copayments | You save on premium but pay more during treatment |
| Headline inpatient limit | Whether maternity, cancer, outpatient care, and chronic conditions sit under smaller limits | A KES 3M limit behaves like a much smaller policy |
The comparison that matters is not premium versus premium. It is benefit structure versus your actual risk profile.
Name, premium, and headline limit cannot tell you whether your maternity sublimit covers delivery at your actual target hospital.
They cannot tell you whether a KES 3M inpatient limit hides a KES 400,000 cancer ceiling inside it.
They cannot tell you whether your preferred hospital costs you KES 1,000 or KES 2,000 every time you walk through the outpatient door.
The best medical insurance companies in Kenya are not the best in the abstract. They are best for your specific situation: your hospital, your family stage, your likely medical events, and the policy wording that applies when you claim.
Four medical insurance details that decide what your family pays at claim time
1. Maternity sublimit vs. your actual hospital
The hidden issue
“Maternity included” is not the same as “maternity sufficient.”
This is one of the most misunderstood parts of maternity cover in Kenya because buyers hear “maternity included” and assume the benefit matches the hospital they intend to use.
Why it matters
The reviewed schedules include maternity benefits either as inbuilt benefits or optional add-ons.
A normal delivery at Aga Khan starts at KES 200,000. A C-section runs from KES 350,000 to KES 600,000 or above. Eight schedules can produce eight different out-of-pocket outcomes.
Check before buying
Before you buy on the basis of “maternity included”:
- Get the exact maternity sublimit in writing.
- Separate the emergency C-section limit from the general maternity limit.
- Confirm whether normal delivery, elective C-section, and emergency C-section are treated differently.
- Hold the limits against a billing estimate from your preferred hospital.
Advisory note: The headline inpatient limit may not govern the maternity claim.
2. The cancer sublimit inside your inpatient limit
The hidden issue
This is the one most professionals never see until the claim.
In most of the reviewed schedules, cancer treatment is governed by the pre-existing/chronic conditions section rather than a standalone cancer line.
Why it matters
Cancer cover in Kenya should not be checked by looking only at the inpatient limit. You need to find:
- The actual cancer ceiling
- The waiting period
- Whether treatment sits under a dedicated benefit
- Whether it shares a chronic/pre-existing sublimit
Heritage HeriAfya is the exception in this review. It lists cancer as its own separate benefit with its own specific sublimit at each plan tier.
Every other insurer in this review requires you to find the cancer ceiling by reading the pre-existing/chronic conditions section — a clause most buyers never open.
Check before buying
Search the policy schedule for the word “cancer.”
If you cannot find a dedicated cancer line, check the pre-existing and chronic conditions section.
Advisory note: Do not assume that a high inpatient limit automatically means a high cancer benefit.
3. The hospital copayment hiding inside your premium
The hidden issue
You chose Aga Khan. You are on your insurer’s panel. You still pay every time you walk in.
Most major insurers apply outpatient copayments at premium private hospitals. The amounts vary, and the differences matter for a family making frequent specialist visits.
Why it matters
Medical insurance copayments are not always obvious when you compare premiums, but they affect the real cost of using your cover at premium hospitals.
What you pay per visit at Aga Khan and Nairobi Hospital — by insurer.
| Insurer | Aga Khan / premium hospital outpatient copay |
|---|---|
| Old Mutual Afyaimara | KES 2,000 per visit |
| APA Jamii Plus | KES 1,500 per visit |
| Heritage HeriAfya | KES 1,000 per visit |
| AAR | KES 1,000 per visit |
| Fidelity | KES 1,000 per visit |
| Jubilee | KES 2,000 per visit |
| Britam | KES 1,500 per visit |
| CIC | KES 2,000 per visit |
| Madison | KES 1,000 per visit |
Copayment figures are indicative and subject to change at renewal. Verify the exact figure on your policy schedule before your next visit — not after.
Five specialist visits per year at Old Mutual, CIC, and Jubilee costs KES 10,000 in copayments alone, before a single treatment is billed.
Check before buying
This is not necessarily a dealbreaker. It is a cost that belongs in your calculation before you sign.
Ask:
- What is the copay at my preferred hospital?
- Is it per visit, per claim, or per service?
- Does it apply to outpatient only or to other benefits too?
- How many outpatient visits does my household realistically make in a year?
4. Outpatient depth vs. your family’s real usage
The hidden issue
The outpatient limit is where many families discover whether their policy fits daily life, not just emergencies.
A specialist consultation at Aga Khan runs KES 4,000–8,000. A diagnostic episode runs KES 15,000–30,000.
A family with two young children can exhaust a KES 50,000 outpatient limit before the year reaches August.
Why it matters
The difference between a KES 50,000 and KES 150,000 outpatient limit feels theoretical when you are buying. It becomes concrete by July.
One structural note from the reviewed schedules: AAR covers chemotherapy and radiotherapy under the outpatient benefit. Most chemotherapy in Kenya is administered as outpatient infusions. On AAR’s Platinum plan, the outpatient limit is KES 250,000 per person.
Whether this is an advantage or a constraint depends entirely on your plan tier and how you expect to use it.
Check before buying
Before choosing a plan, estimate your household’s real outpatient usage:
- Paediatric visits
- Specialist consultations
- Repeat diagnostics
- Chronic medication reviews
- Dental and optical use, where applicable
- Preferred hospital copays
Advisory note: A low outpatient limit may still work for a low-usage household. It is a poor fit for a family using premium private hospitals frequently.
Medical insurance companies in Kenya compared: where selected plans differ at claim time
The plans below sit broadly within the KES 2M–3M inpatient range, but they do not behave the same way at claim time.
A similar inpatient limit can produce very different outcomes once maternity sublimits, cancer waiting periods, cancer ceilings, and premium-hospital copayments are applied.
Figures are taken from insurer benefit schedules, policy brochures, hospital billing estimates where available, and Amssurity’s advisory review process. Benefits, copayments, panel access, and underwriting rules change, so always confirm the current schedule before buying or renewing cover.
Maternity cover, cancer limits, and copayments — side by side.
| Insurer / plan reviewed | Maternity limit / position | Cancer wait | Cancer ceiling | Aga Khan outpatient copay |
|---|---|---|---|---|
| Jubilee J-Care — Advanced, 2M | KES 120K, optional add-on | 2 years | KES 400K, pre-existing sublimit | KES 2,000 per visit |
| APA Jamii Plus — 2M plan | KES 250K max, optional add-on | 12 months | KES 500K, pre-existing sublimit | KES 1,500 per visit |
| AAR — Silver, ~2M | Inbuilt; 1-year wait | N/A — outpatient | Within outpatient limit | KES 1,000 per visit |
| Old Mutual AfyaImara — Option III, 3M | KES 100K, inbuilt | 12 months | KES 700K, pre-existing sublimit | KES 2,000 per visit |
| Britam Milele — Silver | KES 220K, standalone, 10-month wait | 12 months | KES 800K, pre-existing sublimit | KES 1,500 per visit |
| CIC Family Medisure — Superior, 2M | KES 100K, inbuilt | 12 months | KES 500K, shared sublimit | KES 2,000 per visit |
| Heritage HeriAfya — 2M plan | KES 200K max, optional add-on, 8 tiers available | 2 years | KES 750K, separate cancer sublimit | KES 1,000 per visit |
| Fidelity My Afya Shield — Plan C, 2M | KES 100K, optional add-on | 2 years | KES 400K, pre-existing sublimit | KES 1,000 per visit |
| Madison BetterLife Premier — Option III, 3M | KES 200K, inbuilt | 1 year | KES 700K, shared sublimit | KES 1,000 per visit |
Figures are drawn from policy schedules and product guides current at the time of review. Sublimits, waiting periods, and copayments change at renewal — always verify against your specific policy document before making a claim decision.
How to read this table
Do not use this table to pick a winner. Use it to spot the pressure points.
If you are planning maternity, the maternity sublimit and C-section wording matter more than the insurer name.
If cancer protection is a concern, check whether the cancer benefit has its own ceiling or sits inside a chronic/pre-existing sublimit.
If you use premium private hospitals, the outpatient copay changes the real cost of your cover.
If a column says “confirm current schedule,” do not treat the gap as harmless. Treat it as a question that must be answered before you buy or renew.
The table is not the final answer. It is the shortlist of questions to resolve before you buy, renew, upgrade, or switch.
Medical insurance companies in Kenya reviewed: what each plan is best suited for
The reviews below are not rankings. They are claim-time fit notes based on the selected schedules reviewed.
A plan that works well for outpatient-heavy families may be weaker for maternity. A plan with clear cancer wording may still carry a long waiting period. A plan with a familiar insurer name may still need closer review if your family uses premium private hospitals.
Use each review to identify the trade-off, not to crown a universal winner.
Jubilee J-Care medical insurance review
Claim-time read:
Jubilee J-Care may suit buyers who value broad access and brand familiarity, but the maternity and cancer limits need careful testing against real claim scenarios.
Best for:
Buyers who want broad hospital panel access and a recognisable claim-payment track record.
The number:
The maternity sublimit on the mid-range Advanced plan is KES 120,000.
A normal delivery at Aga Khan starts at KES 200,000. That leaves a minimum gap of about KES 80,000 before complications, consultant differences, or room-category changes.
Watch for:
Cancer has a 2-year waiting period and draws from the pre-existing/chronic sublimit, which on Advanced is KES 400,000.
Best fit:
Jubilee may fit buyers who prioritise access and insurer familiarity, but it needs careful review for maternity planning and cancer-risk exposure.
APA Jamii Plus medical insurance review
Claim-time read:
APA Jamii Plus may work well for households that want stronger pre-existing condition support and optional maternity flexibility, but the C-section wording needs close attention.
Best for:
A household with pre-existing conditions wanting relatively generous sublimits, or anyone who wants APA’s Femina Plus cancer cash benefit as a separate safety net.
The number:
Maternity is an optional add-on in five tiers. The highest tier is KES 250,000.
The emergency C-section limit is a separate figure: KES 75,000 on the 2M plan and KES 100,000 on the 10M plan.
An emergency C-section at Aga Khan can run above KES 500,000.
Watch for:
The emergency C-section limit and the general maternity limit are not the same thing.
A buyer who reads only the maternity add-on limit and assumes it covers a C-section fully may be exposed.
The Femina Plus cancer payout is also a cash benefit, not a treatment-cost cover. That distinction matters.
Best fit:
APA may suit buyers who want pre-existing condition support, optional maternity tiers, and additional cash-benefit protection, but families planning delivery at premium hospitals should confirm the C-section limits carefully.
AAR medical insurance review
Claim-time read:
AAR is strongest where outpatient depth is the main concern, but it needs closer review where maternity adequacy, inpatient-heavy events, or chronic waiting periods are the buyer’s primary issue.
Best for:
A household where frequent outpatient use is the dominant concern — paediatric consultations, specialist visits, repeat diagnostics, and routine treatment.
The number:
Outpatient limits run from KES 50,000 to KES 250,000 per person.
Chemotherapy and radiotherapy are included within the outpatient benefit.
AAR’s newly diagnosed chronic waiting period is 6 months, compared with 3 months for most other insurers in this review.
Watch for:
If your main concern is a large inpatient event, maternity delivery at a top-tier facility, or fast access for newly diagnosed chronic conditions, the outpatient-first structure needs careful interrogation.
Best fit:
AAR may fit families that use outpatient care frequently and want stronger day-to-day medical support. It may be less straightforward where the primary concern is maternity adequacy, inpatient exposure, or chronic-condition timing.
Old Mutual AfyaImara medical insurance review
Claim-time read:
Old Mutual AfyaImara has a strong critical illness cash benefit and shorter chronic-condition access, but premium hospital users and maternity-planning families need to price the copays and maternity gap carefully.
Best for:
A household that values a shorter wait for newly diagnosed chronic conditions and wants maternity inbuilt rather than purchased separately.
The number:
The Critical Illness lumpsum pays KES 750,000 cash on first diagnosis of cancer, stroke, heart attack, kidney failure, or paralysis.
That is a genuine additional benefit that no other plan in this review matches at this level.
Watch for:
Old Mutual has a KES 2,000 outpatient copay at both Aga Khan and Nairobi Hospital — the highest of any insurer in this review.
Five specialist visits per year equals KES 10,000 in copayments before a single test is billed.
Maternity sublimit on the 3M plan is KES 100,000.
Best fit:
Old Mutual may suit buyers who value the critical illness cash benefit and shorter chronic-condition access. It needs closer review for families planning maternity or using premium private hospitals frequently.
Britam Milele medical insurance review
Claim-time read:
Britam Milele may suit families that want a structured product range and a 12-month cancer waiting period, but the maternity and critical illness waiting periods must be factored into timing.
Best for:
A family that wants a clearly tiered product range, a 12-month cancer waiting period rather than 2 years, and a standalone maternity benefit that scales to KES 250,000 on the Gold plan.
The number:
Cancer falls under the pre-existing/chronic sublimit, but Britam’s 12-month wait is meaningfully better than Jubilee’s, Heritage’s, and Fidelity’s 2-year wait.
On the Gold plan, the pre-existing/chronic ceiling is KES 1,000,000 — the most generous of the mid-tier plans reviewed.
Watch for:
The Critical Illness Cash benefit has a 24-month waiting period.
The maternity standalone benefit requires a 10-month waiting period.
You also need to confirm the overall inpatient plan limit that corresponds to the pre-existing sublimit you need.
Best fit:
Britam may suit buyers who want structured options, better cancer waiting-period position